India Electronic Warfare Market Executive Summary
The market is projected to grow from USD 742.15 Million in 2025 to USD 1,130.91 Million by 2034 at a CAGR of 4.29% during 2026-2034. This India electronic warfare market analysis shows demand driven by geopolitical threats along sensitive borders, the need to modernize military capabilities, and a strong push for indigenous defense technology. EW equipment commands a 74.5% share, jammers lead the equipment category at 32.5%, electronic support leads capacity at 36.8%, and land platforms hold 34.5%.
North India leads regionally with a 31.5% share, reflecting its proximity to disputed borders. The India electronic warfare market report also highlights a competitive mix of public sector enterprises, defense research laboratories, and private defense firms, with the government steering procurement toward domestic suppliers through Atmanirbhar Bharat and Make in India.
Market Snapshot
Market Size (2025): USD 742.15 Million
Forecast Market Size (2034): USD 1,130.91 Million
CAGR (2026-2034): 29%
Leading Product: EW Equipment (74.5% share, 2025)
Leading Equipment: Jammer (32.5% share, 2025)
Leading Capacity: Electronic Support (36.8% share, 2025)
Leading Platform: Land (34.5% share, 2025)
Leading Region: North India (31.5% share, 2025)
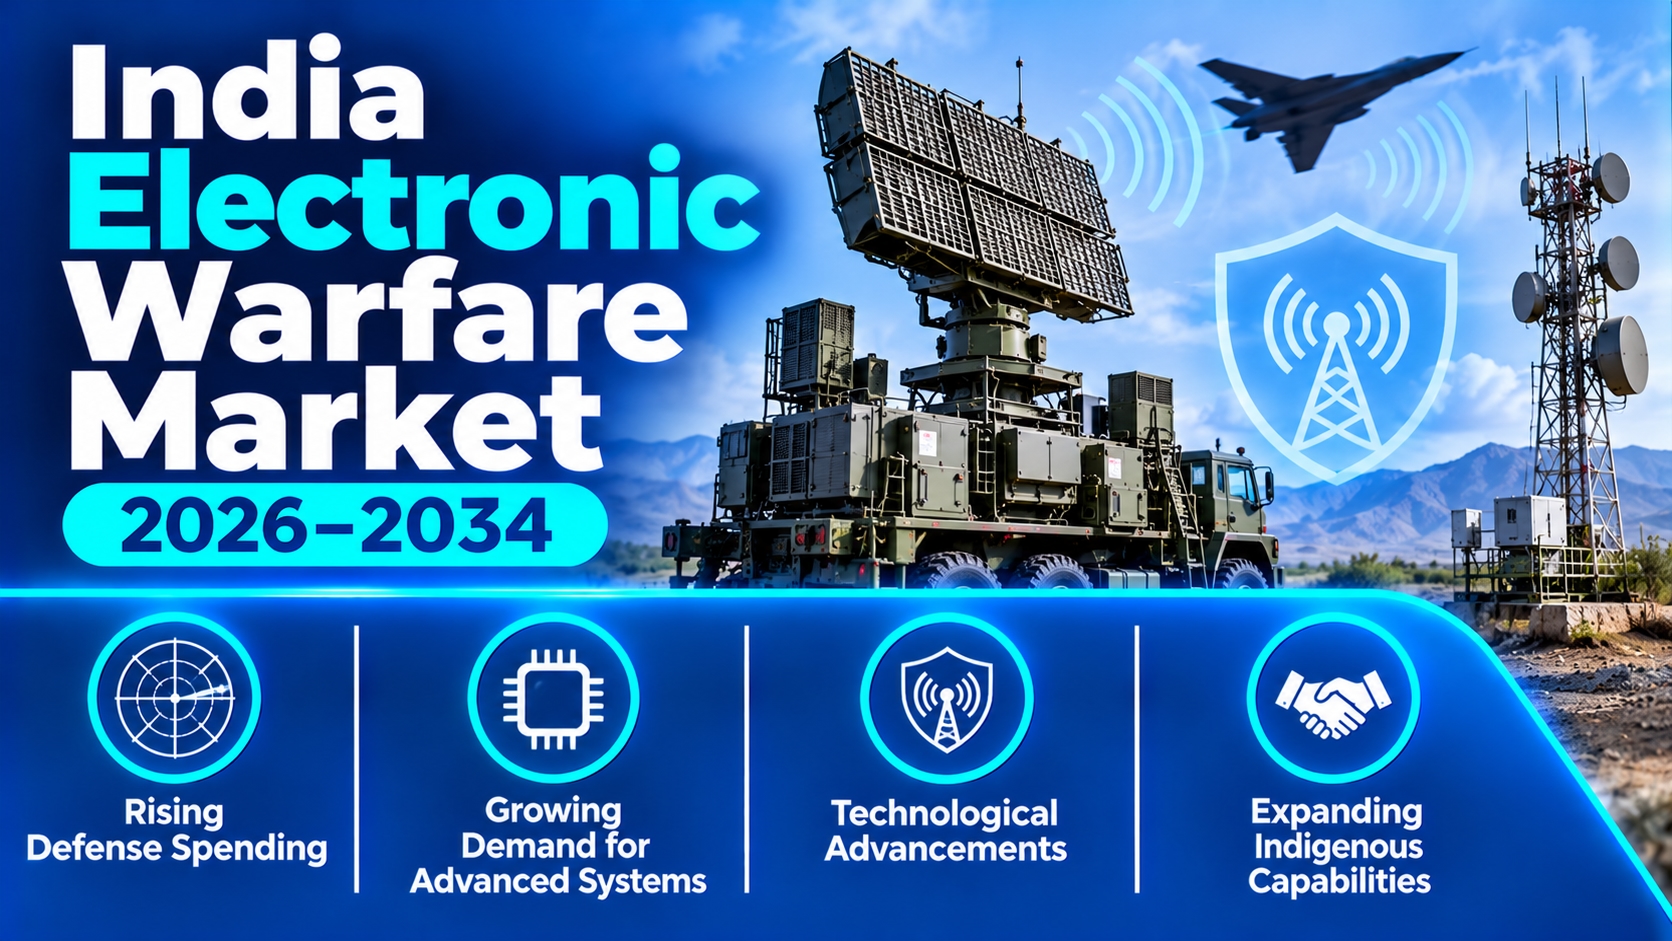
India Electronic Warfare Market Key Drivers
Escalating Geopolitical Tensions and Border Security Imperatives:
Persistent security challenges along northern and western borders sustain demand for advanced electronic warfare. Spectrum dominance is now seen as a prerequisite for operational success, lifting EW from a supporting role to a central part of defense strategy across land, airborne, naval, and space domains.
Government-Led Indigenization and Rising Defense Budgets:
Atmanirbhar Bharat and Make in India are directing procurement toward domestic manufacturers. In 2025, the Indian Air Force issued a Request for Information for 100 advanced ASPJ electronic warfare pods under its Super Sukhoi upgrade project. Defense Industrial Corridors in Uttar Pradesh and Tamil Nadu and positive indigenization lists restricting imports further stimulate local production.
Adoption of AI, Directed Energy, and Advanced Sensing:
In 2025, India tested a 30 kW laser-based directed energy weapon developed by DRDO, showing the ability to disable drones and other aerial threats. AI enables adaptive signal classification, automated threat response, and cognitive jamming.
Supportive Defense Procurement and Innovation Frameworks:
The Defence Acquisition Procedure, the iDEX program, and DRDO’s Technology Development Fund open pathways for startups and MSMEs to compete for EW work.
Evaluate Market Opportunity with the Business Sample Report
India Electronic Warfare Market Emerging Trends
Growing Indigenization of EW Capabilities:
In February 2026, Amitec Electronics inaugurated a dedicated EW manufacturing facility at the Aligarh node of the Uttar Pradesh Defence Industrial Corridor, with an investment of around INR 330 crore, strengthening domestic design and production.
Integration of Artificial Intelligence into EW Platforms:
In July 2024, the Ministry of Defence approved several AI-enabled defense projects under iDEX, including solutions for EW signal intelligence and spectrum monitoring.
Expansion Across Multi-Domain Platforms:
In March 2023, the Government approved expansion of the Indian Air Force’s Integrated Air Command and Control System to integrate sensors, EW inputs, and real-time battlefield data.
Shift Toward Software-Defined, Broadband Jamming:
Software-defined architectures capable of targeting multiple frequency ranges at once are widening the scope of jammer procurement.
India Electronic Warfare Market Challenges
Despite robust momentum, the market faces structural headwinds:
Technological complexity and high development costs, with extended timelines for fielding indigenous systems
Continued reliance on international collaboration in certain critical technology domains
Electromagnetic spectrum congestion and the absence of fully integrated spectrum management across joint forces
Dependence on imported advanced semiconductors, specialized sensors, and high-frequency subsystems, exposing programs to supply chain disruption
Explore the Full Report with Charts, Table of Contents, and List of Figures
India Electronic Warfare Market Segment Insights
By Product
EW Equipment: 74.5%
EW Operational Support
By Equipment
Jammer: 32.5%
Countermeasure System
Decoy
Directed Energy Weapon
Others
By Capacity
Electronic Support: 36.8%
Electronic Protection
Electronic Attack
By Platform
Land: 34.5%
Naval
Airborne
Space
Regional Insights
North India: Share (2025) 31.5%
West and Central India
South India
East and Northeast India
Competitive Landscape
The market is anchored by government-owned defense enterprises and research institutions, with a growing private ecosystem of startups and MSMEs. Public sector undertakings play a dominant role through established manufacturing and large government contracts. Competition is intensifying as procurement sources diversify and indigenization frameworks expand.
Bharat Electronics Limited - Key Focus: Indigenous EW suites for Indian Air Force platforms
Core Strength: Large government contracts and long-standing relationships with the armed forces
Amitec Electronics - Key Focus: Dedicated EW manufacturing at the Uttar Pradesh Defence Industrial Corridor
Core Strength: New domestic production capacity
Unistring Tech Solutions (Zen Technologies subsidiary) - Key Focus: Advanced EW system development for DRDO
Core Strength: Participation in indigenous defense electronics programs
DRDO - Key Focus: Research and technology transfer, including directed energy
Core Strength: Defense research laboratories and test infrastructure
Recent Developments
February 2026: DRDO awarded a ₹30.01-crore contract to Unistring Tech Solutions, a subsidiary of Zen Technologies, to develop an advanced electronic warfare system
February 2026: Amitec Electronics inaugurated its EW manufacturing facility in Aligarh with an investment of around ₹330 crore
2025: India tested a 30 kW laser-based directed energy weapon system developed by DRDO
April 2025: Bharat Electronics Limited signed a ₹2,210-crore contract with the Ministry of Defence for an indigenous EW Suite for Mi-17 V5 helicopters
Investment Opportunities
High-Growth Segments: Jammers, electronic support systems, and countermeasure platforms are central to procurement, with directed energy and satellite-based solutions offering high-value growth.
Geographic Expansion: Defense Industrial Corridors in Uttar Pradesh and Tamil Nadu provide infrastructure and incentives for new production and testing facilities.
Venture & Strategic Investment: AI-enabled signal processing, software-defined radio, and component localization are strong areas for startups and established players.
Request Customized Data Tailored to Your Interest
Frequently Asked Questions (FAQ)
What is the India electronic warfare market size in 2025?
The market was valued at USD 742.15 Million in 2025.
What is the projected market size by 2034?
It is projected to reach USD 1,130.91 Million by 2034 at a CAGR of 4.29% during 2026-2034.
Which product segment leads?
EW equipment leads with a 74.5% share in 2025.
Which region dominates?
North India leads with a 31.5% share in 2025.
What are the major challenges?
High development costs, technological complexity, spectrum management constraints, and import dependence for semiconductor components.
Conclusion
India’s electronic warfare market is on a steady growth path, supported by border security needs, government-backed indigenization, and growing use of AI and directed energy. Modernization across land, airborne, naval, and space platforms ensures long-term procurement demand.
Organizations that invest in indigenous design, software-defined architectures, and resilient component supply chains will be best positioned as India builds a self-reliant defense electronics base.
Source: IMARC Group





