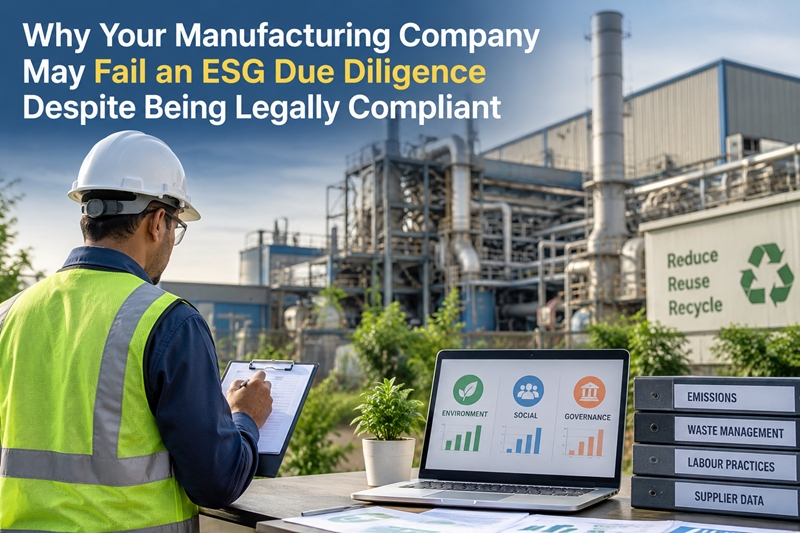
A manufacturing company can have valid licences, environmental approvals, safety procedures and statutory records and still face difficult questions during an ESG due diligence exercise. This does not necessarily mean the company has violated any law. The issue is that legal compliance and ESG due diligence examine different dimensions of business risk.
Legal compliance primarily asks whether applicable requirements are being met. ESG due diligence goes further. It examines whether material environmental, social and governance risks have been identified, managed, measured and supported by credible evidence. For a manufacturer seeking investment, financing, acquisition or major customer relationships, that difference can become commercially important.
Legal Compliance Is the Starting Point, Not the Entire ESG Picture
Consider a factory that has all required environmental permissions and conducts statutory safety inspections. From a regulatory perspective, this may demonstrate compliance with applicable requirements.
An ESG reviewer may ask additional questions:
How are the company's most significant environmental risks identified?
Who is accountable for ESG performance?
Is energy consumption measured against production output?
How are worker and contractor safety risks monitored?
Are suppliers screened for material ESG risks?
Can reported ESG data be traced back to source records?
Are identified problems followed by documented corrective actions?
Does management periodically review ESG performance?
This distinction is consistent with established environmental and social risk-management approaches. IFC's Environmental and Social Management System framework, for example, treats environmental, occupational health and safety, labour and community risks as interconnected management responsibilities rather than isolated compliance activities.
The practical implication: having the required documents does not automatically demonstrate that the underlying ESG risks are being systematically managed.
10 Reasons a Legally Compliant Manufacturer Can Still Have ESG Due-Diligence Gaps
1. Compliance Activities Are Fragmented Across Departments
Manufacturing companies often manage environmental, safety, HR, procurement and financial information separately. Each department may be performing its responsibilities correctly, yet there may be no integrated ESG risk-management system.
For example, EHS may track incidents, Finance may maintain utility bills, HR may hold workforce information and Procurement may manage supplier records. An investor asking for a consolidated ESG assessment can expose gaps between these systems.
The problem is therefore not necessarily missing information. It is lack of integration, ownership and consistency.
2. ESG Data Cannot Be Traced Reliably
A company may possess electricity bills, fuel records, water consumption figures, waste manifests, employee records and accident statistics. The difficulty begins when someone asks how a particular ESG figure was calculated.
Common weaknesses include:
inconsistent measurement units between plants
different reporting periods
manual spreadsheet consolidation
undocumented estimation methods
unclear data ownership
missing supporting records
changes in calculation methodology
A credible ESG number should have a clear trail from the reported figure back to its source.
This becomes particularly relevant as ESG disclosures increasingly place emphasis on reliable, reviewable information. SEBI's BRSR Core framework introduced a structured set of key ESG indicators and a phased assessment/assurance approach for larger listed entities.
3. Policies Exist, but Evidence of Implementation Is Weak
An ESG policy, human-rights policy, supplier code or safety policy can demonstrate management intent. It does not, by itself, demonstrate implementation.
A reviewer may therefore look for evidence such as:
training records
inspection results
corrective-action registers
management reviews
grievance records
supplier assessments
incident investigations
performance trends
This distinction matters because sustainability commitments can be easier to document than actual risk-management outcomes. OECD's 2026 research highlights an implementation gap in responsible-business due diligence, including weaknesses in demonstrating actual risk identification and mitigation.
A useful test is simple: if a policy says something is being managed, can the plant show how it is being managed?
4. Supplier Risks Are Not Visible Beyond Tier-1 Vendors
A manufacturer may have strong internal controls while remaining exposed to risks originating in its supply chain.
Potential issues can involve:
labour practices
occupational safety
environmental performance
responsible sourcing
waste handling
resource consumption
inaccurate sustainability claims
This is particularly relevant to manufacturing because complex supply chains can involve multiple tiers. SEBI's work on value-chain disclosures has recognised the difficulty of obtaining ESG information from business partners and the significance of value-chain impacts.
Supplier ESG management therefore should not stop at collecting a declaration or certificate. Higher-risk suppliers may require deeper assessment based on their activities, location, materials and relationship with the manufacturer.
5. Certifications Are Treated as a Substitute for Risk Assessment
ISO certifications and other recognised credentials can provide useful evidence of management-system practices. However, they should not automatically be treated as proof that every material ESG risk has been addressed.
For example, certification may demonstrate conformity with a particular standard, while an investor may still want to understand:
actual performance trends
unresolved incidents
resource consumption
contractor practices
supplier risks
corrective actions
site-specific risks
OECD guidance similarly cautions against treating sustainability initiatives or certifications as a substitute for a company's own responsible-business due diligence.
Speak With An Expert: https://www.imarcengineering.com/contact?service=esg-compliance
6. Contractor Workforce Risks Are Overlooked
Manufacturing operations frequently depend on contractors for maintenance, logistics, housekeeping, security, construction and other activities.
A company may have robust systems for permanent employees but weaker visibility over contract workers.
An ESG review may therefore examine:
safety induction
PPE provision
training
working conditions
incident reporting
emergency preparedness
grievance mechanisms
contractor compliance monitoring
For high-risk industrial activities, this distinction can be significant because the operational risk remains connected to the manufacturing site even when the worker is employed by another organisation.
7. Safety Compliance Does Not Equal Mature Risk Management
A factory may have fire equipment, PPE, emergency procedures and statutory inspection records. A deeper assessment can ask whether the company systematically identifies and controls its highest-risk activities.
This can involve:
hazard identification and risk assessment
job safety analysis
process-safety controls
emergency response planning
incident investigation
root-cause analysis
corrective-action tracking
contractor safety
IFC assessments of Indian manufacturing projects demonstrate how environmental and social reviews can extend into areas such as occupational health and safety, emergency response, HAZOP, risk assessment and environmental monitoring.
8. Environmental Compliance Is Strong, but Resource Performance Is Poorly Managed
Meeting a permitted environmental limit answers one question: whether the operation is within the applicable requirement.
ESG due diligence can ask a broader set of questions:
Is energy consumption declining or increasing?
How much energy is consumed per unit of production?
How efficiently is water being used?
What proportion of waste is recovered?
Where are the largest environmental improvement opportunities?
Are environmental targets supported by baseline data?
Resource efficiency and pollution prevention are explicitly included within IFC's environmental and social performance framework.
The key difference is between compliance performance and improvement performance.
9. Material ESG Issues Have Not Been Prioritised
Not every ESG issue carries the same level of risk for every manufacturer.
A chemical manufacturer may face significant process-safety, hazardous-material and water risks. An electronics manufacturer may have greater exposure to e-waste, responsible sourcing and supply-chain risks. A food processor may need greater focus on water, waste, packaging and labour practices.
A generic ESG checklist can therefore create a large amount of information without identifying what matters most.
A more useful approach is:
Business activity → Potential impact → Risk → Materiality → KPI → Control → Evidence
This makes ESG assessment relevant to the actual manufacturing operation rather than a collection of generic questions.
10. The Company Cannot Substantiate Its ESG Claims
Ultimately, many due-diligence problems come down to evidence.
Suppose a company reports that energy intensity improved by 12%. A reviewer may reasonably ask:
What baseline year was used?
Which facilities are included?
How was production normalised?
What energy sources were included?
Were estimates used?
Who owns the data?
What source documents support the calculation?
A mature ESG system connects each important claim to its metric, methodology, owner, source data and supporting evidence.
What Investors and Lenders May Examine
ESG due diligence can vary according to the transaction, sector, geography and investor's requirements. However, a manufacturing assessment may cover:
Area | Questions May Focus On |
|---|---|
Governance | Accountability, policies, oversight and controls |
Environment | Energy, emissions, water, waste and pollution |
EHS | Hazards, incidents, emergency preparedness and controls |
Workforce | Labour practices, training and worker conditions |
Contractors | Safety and workforce management |
Supply chain | Supplier screening and ESG risks |
Data | Methodology, consistency and evidence |
Compliance | Permits, approvals and regulatory records |
Corrective action | Open findings, responsibilities and closure |
Stakeholders | Grievances and community-related risks |
The exact scope should be determined by the transaction and the material risks of the business rather than by treating every ESG issue equally.
How to Prepare Before an ESG Due Diligence Exercise
A manufacturer does not need to wait for an investor questionnaire to discover its gaps. A practical preparation process can follow seven stages:
1. Establish the regulatory baseline
Map applicable environmental, safety, labour and other statutory requirements separately from broader ESG expectations.
2. Identify material ESG risks
Prioritise issues according to the company's processes, resources, workforce, supply chain and locations.
3. Conduct an ESG gap assessment
Compare current practices, data and controls against the expectations relevant to the company.
4. Assign data ownership
Define who is responsible for each ESG metric across EHS, HR, Finance, Operations, Procurement and other functions.
5. Build evidence trails
Maintain the source, calculation methodology, responsible owner and supporting records for significant ESG information.
6. Assess higher-risk suppliers
Use a risk-based approach rather than applying identical scrutiny to every supplier.
7. Convert gaps into corrective actions
Each significant gap should have an owner, priority, corrective action, target date and method of verification.
How IMARC Engineering Can Help
IMARC Engineering can support manufacturing companies in moving from fragmented compliance records to a structured ESG management approach. The work can include ESG baseline assessment, materiality assessment, regulatory and requirement mapping, gap identification, KPI and data-system development, risk prioritisation and ESG roadmap preparation. The objective is to help management understand where material gaps exist, what evidence is available, which improvements should be prioritised and how ESG responsibilities can be integrated into plant-level operations.
Conclusion
Legal compliance remains essential, but it should not be confused with complete ESG readiness. A manufacturing company can meet statutory requirements and still have weaknesses in ESG data, supplier oversight, workforce management, resource efficiency, governance or evidence. Preparing early allows these gaps to be identified and addressed before they become transaction or stakeholder issues. A practical ESG due diligence approach therefore connects risk identification, management controls, measurable performance and credible evidence rather than relying only on licences, policies or certifications.
Contact Us:
IMARC Engineering
Phone: +91-120-433-0800
Email: sales@imarcengineering.com
India: C-130, Sector 2, Noida, Uttar Pradesh 201301
LinkedIn: https://www.linkedin.com/showcase/imarc-engineering/