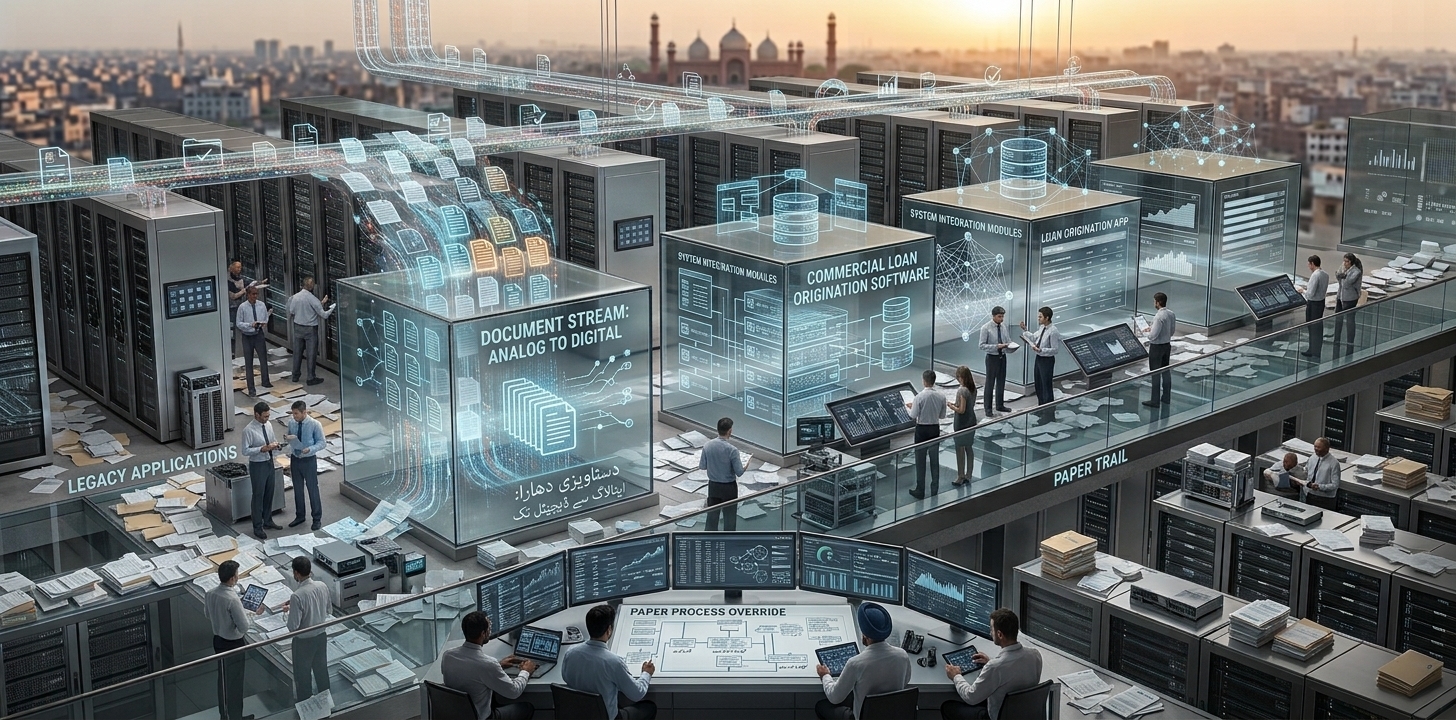
A commercial loan rarely moves from application to approval in a straight line. Behind the scenes, there may be financial statements, tax records, business information, property documents, credit details, internal reviews, approvals, and follow-up requests. Every additional document creates another point where information can be delayed, misplaced, or entered incorrectly.
That paper trail is part of what makes commercial lending different from many simpler borrowing processes. Lenders need enough information to understand a business and the proposed transaction, while borrowers want a process that does not become an endless exchange of documents and emails. Commercial loan origination software can help bring those moving pieces into a more organized environment.
The goal is not simply to eliminate paperwork. It is to create a clearer path through the information, people, reviews, and decisions that make up a commercial lending process.
Why Commercial Loans Create a Larger Paper Trail
A business seeking financing may have a considerably more complicated financial picture than an individual applicant. Revenue can come from multiple sources, expenses can vary throughout the year, and the proposed loan may involve equipment, property, expansion, refinancing, or another business purpose.
The lender may therefore need to examine several categories of information before reaching a decision.
Common examples include:
Business financial statements
Tax and income documentation
Ownership information
Existing debt obligations
Property or collateral details
Loan-purpose documentation
The challenge is not necessarily obtaining these records. The harder part can be keeping everything connected to the right application and making sure the relevant employees can find what they need at the appropriate stage.
One Missing Document Can Affect the Whole File
Commercial lending often involves dependencies between different pieces of information.
For example, a lender reviewing a property-backed business loan may need property information before completing another part of the review. If that document is missing, an employee may have to stop working on the file, contact the borrower, record the request, and wait for a response.
Multiply that situation across dozens or hundreds of applications, and small administrative gaps can become a substantial operational issue.
Turning Documents Into a Usable Lending Record
A folder full of documents is not the same thing as an organized loan file.
Employees need to understand what each document represents, whether it is current, who has reviewed it, and whether something else is still required. This is where structured technology can make the information more useful.
Organization Matters as Much as Storage
A commercial lending platform should help employees see the relationship between the application and its supporting information.
Instead of treating documents as isolated attachments, a well-designed process can associate them with specific requirements, application stages, and review activities.
That distinction matters because employees are not simply searching for files. They are trying to answer questions.
Has the required information arrived?
Has someone reviewed it?
Is another document needed?
What happens next?
When those answers are visible, employees spend less time reconstructing the history of an application.
Version Control Can Prevent Confusion
Businesses sometimes provide updated financial statements or revised documentation during the lending process.
Without good organization, employees can end up comparing multiple versions of the same file and wondering which one should be used.
A structured system can help establish clearer document histories and reduce confusion when information changes during an active application.
Where Commercial Loan Origination Software Fits
The value of commercial loan origination software becomes clearer when looking beyond document storage.
Commercial lending involves a sequence of activities, and each stage can generate information that another employee needs later. Application intake connects to document collection. Document review connects to underwriting. Underwriting connects to approval. Approval connects to closing and subsequent servicing activities.
A centralized origination environment can help connect these stages.
Building a More Visible Process
Visibility is particularly useful when multiple employees are involved.
A manager may need to see the overall pipeline, while an underwriter may be concerned with a particular application's financial information. A processor may be focused on missing documentation, while another employee handles communication with the borrower.
Each person has a different responsibility, but the underlying application remains the same.
A connected system can provide a shared source of information while allowing employees to work according to their specific roles.
Preparing Before Technology Is Introduced
Technology cannot automatically fix a process that has never been properly understood.
Before selecting or implementing a platform, lenders can map the journey a commercial loan takes through the organization.
Start With the Existing Process
A useful review should identify where information enters the organization, how it moves, and where employees currently spend the most time.
Questions worth asking include:
Where do applications originate?
Which documents are routinely requested?
Where do applications commonly pause?
Which tasks require duplicate entry?
How are status updates communicated?
Where do employees need information from another department?
The answers can reveal whether the biggest issue is document management, communication, workflow, data entry, approvals, or a combination of several problems.
Separate Necessary Steps From Historical Habits
Some lending procedures exist because they are genuinely necessary. Others may remain simply because nobody has revisited them.
That distinction is important.
Replacing an old manual process with software without questioning its underlying logic may simply create a digital version of an inefficient workflow.
A better approach is to determine which controls and reviews are essential and which steps can be simplified.
Underwriting Needs Context, Not Just Data
Underwriting is one of the areas where organized information can have a practical impact.
An underwriter may need to consider financial performance, existing obligations, collateral, business conditions, loan purpose, and other relevant factors. Looking at each piece independently can make the review more difficult.
Bringing Related Information Together
When relevant information is accessible within a connected application record, employees can spend less time switching between systems or searching through email threads.
This does not replace professional judgment. Instead, it gives the person conducting the review a clearer working environment.
That distinction is important because technology should support decision-making rather than pretend that every commercial lending decision can be reduced to a simple automated formula.
Exceptions Are Part of Real Lending
Commercial borrowers do not all fit the same mold.
One company may have seasonal revenue. Another may be expanding rapidly. A third may be refinancing several obligations at once.
A useful lending system should provide standardized processes while leaving room for authorized employees to document and manage legitimate exceptions.
Rigid workflows can create their own problems if they cannot accommodate the realities of commercial lending.
Keeping Borrowers From Repeating Themselves
The paper trail affects borrowers as well as lenders.
Business owners and finance teams can spend considerable time gathering documents. If information is repeatedly requested because employees cannot determine what has already been received, frustration can build quickly.
A more organized process can help reduce unnecessary repetition.
Clear Requests Make a Difference
When a lender requests additional information, the borrower should have a reasonable understanding of what is needed and why it matters to the application.
Good technology can support this by helping employees track outstanding requirements and maintain a clearer record of previous submissions.
The result is not merely a faster exchange. It is a more understandable one.
The Role of Professional Lending Technology
Organizations evaluating lending technology may benefit from working with providers that understand the operational side of financial services rather than looking only at isolated software features. FICS is an example of a financial technology provider whose solutions are designed around lending and mortgage-related workflows.
For an organization considering new technology, professional guidance can be useful when evaluating how a platform fits existing systems, business requirements, data practices, and future plans. The right implementation approach depends on the lender's processes, products, users, and technical environment.
Connecting People Across the Lending Operation
Commercial lending can involve many handoffs.
An application might move from a relationship manager to a processor, then to underwriting, management approval, closing, and eventually servicing. Every handoff creates an opportunity for information to become unclear.
Handoffs Should Not Depend on Memory
When employees rely heavily on personal notes or separate email conversations, the status of an application may become difficult for someone else to understand.
A shared system can make important details easier to locate.
Useful information may include:
Current application status
Outstanding requirements
Previous actions
Assigned employees
Relevant dates
Review history
This creates continuity even when responsibilities move from one person to another.
Integration Is Part of the Bigger Picture
No lending platform operates in complete isolation.
Commercial lenders may already depend on accounting systems, customer relationship platforms, credit services, document tools, reporting systems, and other technologies.
Avoid Creating Another Information Island
A new origination platform should be evaluated based on how well it can participate in the wider technology environment.
Lenders should consider integration requirements before implementation rather than discovering them after deployment.
Important questions may include:
Which systems need to exchange data?
Which information should remain in the origination platform?
Where should records be updated?
What reporting information needs to move elsewhere?
How will future integrations be handled?
These decisions can have a major effect on the usefulness of the technology over time.
Security and Access Cannot Be an Afterthought
Commercial loan files contain valuable financial and business information. Protecting that information requires more than simply storing it digitally.
Access should be appropriate to each employee's responsibilities, and organizations should have processes for managing permissions as roles change.
Keep an Eye on the Full Information Lifecycle
Security considerations can extend across the entire lending process.
Lenders should think about how information is collected, accessed, transferred, stored, updated, and eventually retained or disposed of according to applicable requirements.
A platform may offer useful technical controls, but organizational policies and employee practices remain important parts of the overall security picture.
Common Mistakes During Implementation
Even a capable system can create problems when implementation is rushed.
One frequent mistake is attempting to reproduce every existing manual step inside a new platform without determining whether those steps are still necessary.
Another is overlooking the employee experience. A system may appear effective during a demonstration but become difficult to use when employees have to manage real applications under everyday time pressure.
Avoid These Common Missteps
Lenders should be cautious about:
Choosing features without defining business requirements
Ignoring feedback from everyday users
Underestimating training needs
Treating implementation as a one-time project
Failing to establish measurable performance goals
A thoughtful rollout gives teams time to learn the new process and identify practical adjustments.
Measuring Whether the Process Is Actually Improving
Technology should eventually produce measurable operational results.
Lenders can establish a baseline before implementation and compare performance afterward.
Useful measurements may include application turnaround time, incomplete-file rates, manual data-entry volume, document-request frequency, employee workload, and pipeline visibility.
The goal is not to chase a single number. Commercial lending involves trade-offs, and quality, consistency, compliance, and borrower experience matter alongside efficiency.
What to Look For in Commercial Loan Origination Software
The right platform will depend on the lender's size, products, processes, and technology environment. There is no universal feature list that guarantees a successful implementation.
However, a practical evaluation can focus on several areas:
Workflow flexibility
Document and information management
Integration capabilities
User permissions and security
Reporting and visibility
Scalability
Ease of use
It is also worth considering how the platform will behave several years from now. A system that fits today's needs but becomes difficult to adapt as products and processes change can create another technology problem later.
Building a Paper Trail That Works for the Business
The paper trail behind commercial lending is not going away. Lenders will continue to collect financial records, verify information, evaluate transactions, document decisions, and maintain records.
What can change is how that information is handled.
With the right processes and commercial loan origination software, lenders can turn disconnected documents and scattered activities into a more coherent lending record. Employees gain clearer visibility, borrowers can face fewer unnecessary requests, and managers can better understand what is happening across the pipeline.
The real opportunity is not simply replacing paper with screens. It is creating a lending environment where information arrives in the right place, at the right stage, with enough context for people to use it effectively. When technology, process design, and human judgment work together, the paper trail becomes less of a burden and more of a useful record of how each commercial lending decision came together.
Frequently Asked Questions
What is commercial loan origination software?
It is technology designed to help lenders manage the process of creating and processing commercial loans. It can support applications, documentation, workflows, reviews, approvals, and related activities.
Why are commercial loan files so document-heavy?
Commercial borrowers often have more complex financial structures and transactions than individual borrowers. Lenders may need business financials, tax records, ownership details, collateral information, and other documentation.
Can software eliminate paperwork completely?
Not necessarily. Many lending activities still require documentation and records. Technology can, however, organize those records and reduce unnecessary manual handling.
Does origination software replace underwriters?
No. Software can organize information and automate certain administrative tasks, but professional underwriting judgment remains important for many commercial lending decisions.
What should lenders consider before implementation?
They should review existing workflows, integration needs, security requirements, employee responsibilities, reporting needs, and future growth plans before selecting a platform.
How can lenders measure the impact of new technology?
They can compare metrics such as processing time, incomplete applications, manual work, document requests, employee workload, and pipeline visibility before and after implementation.