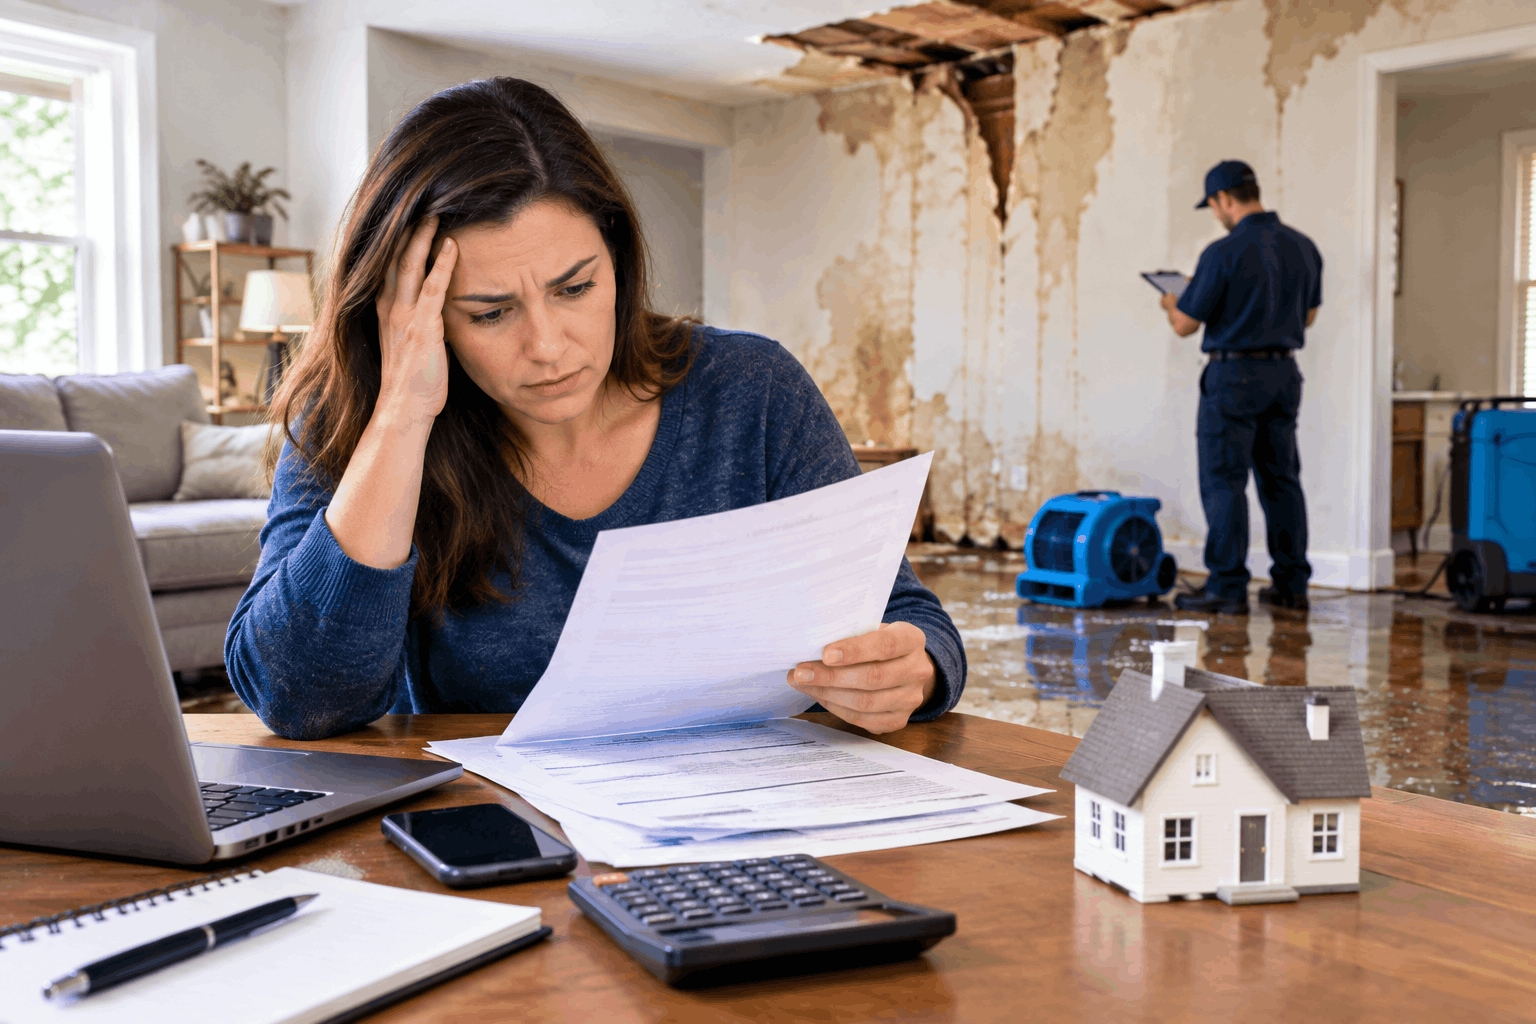
Quick answer first: the biggest insurance mistake homeowners make after water damage is moving too fast to clean up before documenting anything, followed closely by underestimating the scope of damage and assuming mold is automatically covered. Each of these mistakes either delays a claim, reduces the payout, or gets it denied outright. Here's what actually goes wrong and how to avoid it.
The Short Answer Before the Full Breakdown
1. The Mistake That Costs Homeowners the Most
Cleaning up damage before photographing it thoroughly is the single most common and most costly mistake. Insurance adjusters work from evidence, not descriptions, and once carpet is ripped out or drywall is patched, the proof of the original damage is gone along with it.
2. Why Timing Matters as Much as the Claim Itself
Most policies have specific windows for reporting damage, and delays can raise red flags even when the damage itself is legitimate. Waiting a week to report a leak "because it didn't seem that bad at first" is a common story adjusters hear right before a claim runs into trouble.
Mistakes Made in the First 24 Hours
1. Waiting Too Long to Report the Damage
Homeowners often wait to see how things look after a day or two before calling their insurer, hoping it'll resolve itself or turn out to be minor. That delay can work against you, since most policies require prompt reporting, and insurers may question why help wasn't sought sooner if mold or structural issues show up later.
2. Cleaning Up Before Documenting Anything
The instinct to clean up immediately is understandable, nobody wants to live with a soaked carpet, but doing so before taking photos and videos removes the exact evidence an adjuster needs to approve a fair payout. Document everything first, standing water, affected walls, damaged belongings, before touching anything.
Throwing Away Damaged Items Too Early
Ruined furniture, soaked rugs, and waterlogged boxes often get tossed out within the first day simply because they're in the way. Insurers typically want proof of damaged personal property before it's discarded, so photograph everything and check with your adjuster before throwing items away, even ones that are obviously ruined.
Mistakes Made During the Claims Process
1. Underestimating the Scope of the Damage
Homeowners frequently report only the visible damage without realizing water has spread further than what's immediately obvious. This leads to a claim that undervalues the actual repair cost, and reopening a claim later for damage that "should have been caught the first time" is far harder than getting it right from the start.
2. Accepting the First Offer Without Question
Initial settlement offers aren't always the final word, and homeowners sometimes accept them quickly just to move the process along. If an offer seems low compared to actual repair estimates, it's worth requesting a second assessment or getting an independent estimate from a water damage restoration St Louis provider before signing off.
3. Not Understanding What Your Policy Actually Covers
Standard homeowners insurance often distinguishes between sudden water damage, like a burst pipe, and gradual damage from a slow leak that went unnoticed for months. Gradual damage is frequently excluded or covered differently, which catches a lot of homeowners off guard when they assume all water damage falls under the same coverage.
Mistakes Related to Mold and Hidden Damage
1. Assuming Mold Is Automatically Covered
This is one of the most common and expensive misunderstandings. Many policies cap mold coverage significantly lower than general water damage coverage, or exclude it entirely if the mold resulted from a maintenance issue rather than a sudden event. Checking your policy's specific mold provisions before you ever need them saves a lot of frustration later.
2. Ignoring Mold Until It Becomes a Bigger Claim
A small mold patch that gets ignored for weeks often grows into a situation requiring extensive remediation, sometimes including things like attic mold removal if ventilation issues let moisture spread unnoticed. Insurers may view delayed action as a failure to mitigate damage, which can reduce or complicate the payout for the expanded scope.
3. Skipping Professional Testing to Save Money
Some homeowners skip professional air quality testing to save on upfront cost, only to end up with an insurance dispute over whether mold was present and how extensive it actually was. Professional testing creates the documentation carriers actually want to see, which matters just as much for a routine claim as it does for something more involved like attic mold removal after a hidden leak.
How to Avoid These Mistakes Going Forward
1. Building a Documentation Habit Before You Need It
Take photos of your home's condition periodically, especially in basements, attics, and areas with a history of moisture concerns. Having a clear baseline makes proving storm or leak-related damage far easier than trying to explain "before" from memory during a stressful claim process.
2. Working With Professionals Who Know What Carriers Expect
Choosing a company trained specifically in what insurance carriers want to see makes a real difference in how smoothly a claim goes through. Gateway Water and Mold builds Xactimate-aligned scopes with photo documentation and drying logs included, rather than leaving homeowners to piece together evidence after the fact. Professional water damage restoration St Louis services that understand this process reduce the odds of a kicked-back claim significantly, and the same applies whether the situation is standard water extraction or something more specific like attic mold removal that needs its own documentation trail. Working with a water damage restoration St Louis team from the start, rather than after a denied claim, tends to produce a smoother result overall.
Conclusion
Insurance claims after water damage go wrong more often from avoidable mistakes than from complicated policy language. Reporting damage promptly, documenting everything before cleanup, understanding what your policy actually covers, and taking mold seriously from the first sign all make the difference between a smooth claim and a drawn-out dispute. A little preparation and the right documentation habits go a long way toward making sure you get paid fairly for damage that was never your fault to begin with.
Frequently Asked Questions
1. How quickly should I report water damage to my insurance company?
As soon as possible, ideally within a day or two. Most policies expect prompt reporting, and delays can raise questions even when the damage is legitimate.
2. Is mold damage always covered under a standard homeowners policy?
Not always. Many policies cap mold coverage at a lower amount than general water damage or exclude it if it resulted from a maintenance issue rather than a sudden event.
3. Should I throw away damaged items before an adjuster sees them?
No. Photograph everything first and check with your adjuster before discarding damaged belongings, since insurers typically want proof of the loss before items are removed.
4. What should I do if my insurance settlement offer seems too low?
Request a second assessment or get an independent estimate from a professional water damage restoration St. Louis provider to compare against the initial offer before accepting it.
5. Can delaying mold cleanup actually hurt my insurance claim?
Yes. Insurers may view delayed action as a failure to mitigate damage, which can reduce payout for an expanded scope, including situations that grow into something like attic mold removal.